It is 4:30 p.m. on a July afternoon, and your tech has just presented a homeowner with a $12,000 estimate for a full AC replacement. The homeowner agrees the system needs to be replaced but says, “I need to think about it.”
Two days later, he signs with a competitor charging $12,200. Why? That competitor offered a high-efficiency system for $168 a month with instant mobile approval.
When homeowners have no way to spread out a high upfront cost, many will hesitate, delay, or look for a competitor who makes the math easier. Offering integrated HVAC contractor financing removes that friction, protects margins from unnecessary discounting, and gives techs a real path to closing high-ticket jobs in the driveway.
What Is HVAC Contractor Financing?
HVAC contractor financing allows an HVAC business to offer customers structured payment plans for repairs, replacements, and installations through a financing provider, lender, or manufacturer program.
This way, the client does not need to make full payment at the time of service. The business can offer approved customers financing terms that spread the purchase over time. Depending on the provider, the contractor may also have access to digital applications, prequalification, and promotional offers.
For HVAC businesses, financing is most relevant for larger jobs such as full system replacements, furnaces, heat pumps, and major installations. When built into a strong estimating workflow, it becomes a part of how the tech presents and closes the job.
What Happens to High-Ticket Jobs When Financing Is Not on the Table
Not every lost HVAC job is the result of poor service, an overpriced estimate, or a competitor offering better equipment. Sometimes, the customer simply cannot absorb the upfront cost at that moment. When techs can't break down big numbers in the driveway, jobs stall.
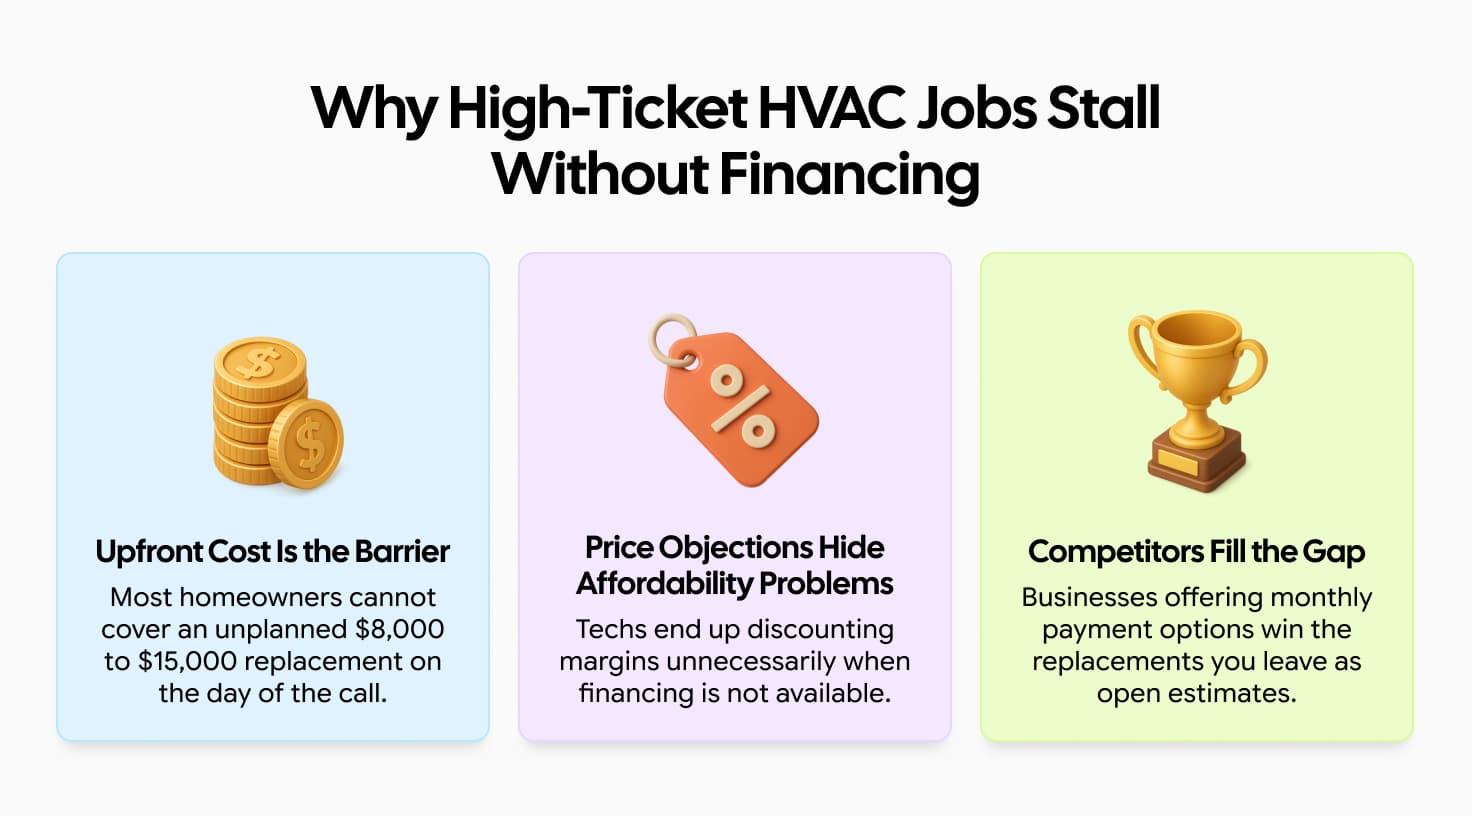
Most Homeowners Cannot Pay $8,000 to $15,000 Out of Pocket on the Day of the Call
Major system failures are unexpected emergencies, and most homeowners do not keep $8,000 to $15,000 in liquid funds ready to spend on an unplanned HVAC replacement. Without a payment option, even a willing customer can stall on a decision they genuinely intend to make.
Price Objections Are Affordability Issues in Disguise
When a customer says an estimate is too high, they are rarely questioning the value of the work. Without financing options to spread out payments, technicians often discount labor and equipment margins unnecessarily to save the job.
Competitors Who Offer Financing Win the Replacements You Walk Away From
Leaving an open estimate for a customer to consider gives local competitors an advantage. Businesses offering clear monthly payment options make high-ticket replacements accessible and win the job on the spot.
Types of HVAC Contractor Financing You Can Offer
HVAC businesses can offer different financing options depending on the type of jobs they sell, their equipment partnerships, and the needs of their customers. The key is understanding where each option fits best in your sales process.
Financing Option | How It Works | Best Use Case |
Third-Party Lender Financing | Customers apply through providers such as Wisetack or Sunbit, often through a digital application during the sales process. | Emergency replacements, major repairs, full system installations. |
Manufacturer-Backed Financing | Financing is offered through participating HVAC equipment dealers and manufacturer programs. | New installations involving specific brands such as Carrier, Trane, or Bryant. |
Same-as-Cash Plans | Customers receive promotional financing terms, such as 0% interest for a defined period when applicable conditions are met. | Planned system upgrades and seasonal replacements. |
How to Present Financing Without It Feeling Like a Sales Pitch
Financing works best when it is treated as a standard payment option rather than a rescue tactic for customers who reject the price. The timing and presentation matter as much as the financing itself.
1. Introduce It at the Estimate Stage, Before Any Price Objection Surfaces
Do not wait until the homeowner says the estimate is too expensive.
If financing is only introduced after resistance appears, it can feel like a last-minute sales tactic. Instead, make payment options part of every estimate conversation.
Your tech can explain the recommendation, walk through the proposal, and then say that flexible payment options are available if the customer prefers to pay over time.
That makes financing normal rather than defensive.
2. Present Monthly Payment Alongside Total Price, Not Instead of It
Customers should always understand the total project price.
Showing only a monthly payment can create confusion and reduce trust. A better approach is to present both numbers together.
For example:
This gives the homeowner the complete financial picture while helping them understand how financing could fit their budget.
3. Use Good/Better/Best Tiers With a Financing Option at Each Level
A single estimate forces customers into a simple yes-or-no decision.
A Good/Better/Best proposal creates a more useful conversation. The homeowner can compare equipment options, features, and prices while also considering available payment options at each tier.
For example:
Good: Standard system replacement
Better: Higher-efficiency system with additional features
Best: Premium system with maximum efficiency and comfort features
Instead of asking whether the customer wants to spend $12,000, the conversation becomes about which solution and payment structure best fits their needs.
Presenting tiered proposals gives homeowners the ability to evaluate equipment options, efficiency levels, and payment structures at the same time, turning a binary price decision into a more useful conversation about what fits their home and budget.
Workiz supports tiered proposals and financing options inside the estimate workflow, helping techs present choices without jumping between multiple tools.
Why Financing Closes More Jobs When It Lives Inside the Estimate, Not Outside It
The longer a customer has to leave the buying process to figure out payment, the more likely the sale is to slow down. That is why financing should be connected to the estimate and customer conversation rather than handled as a completely separate process.
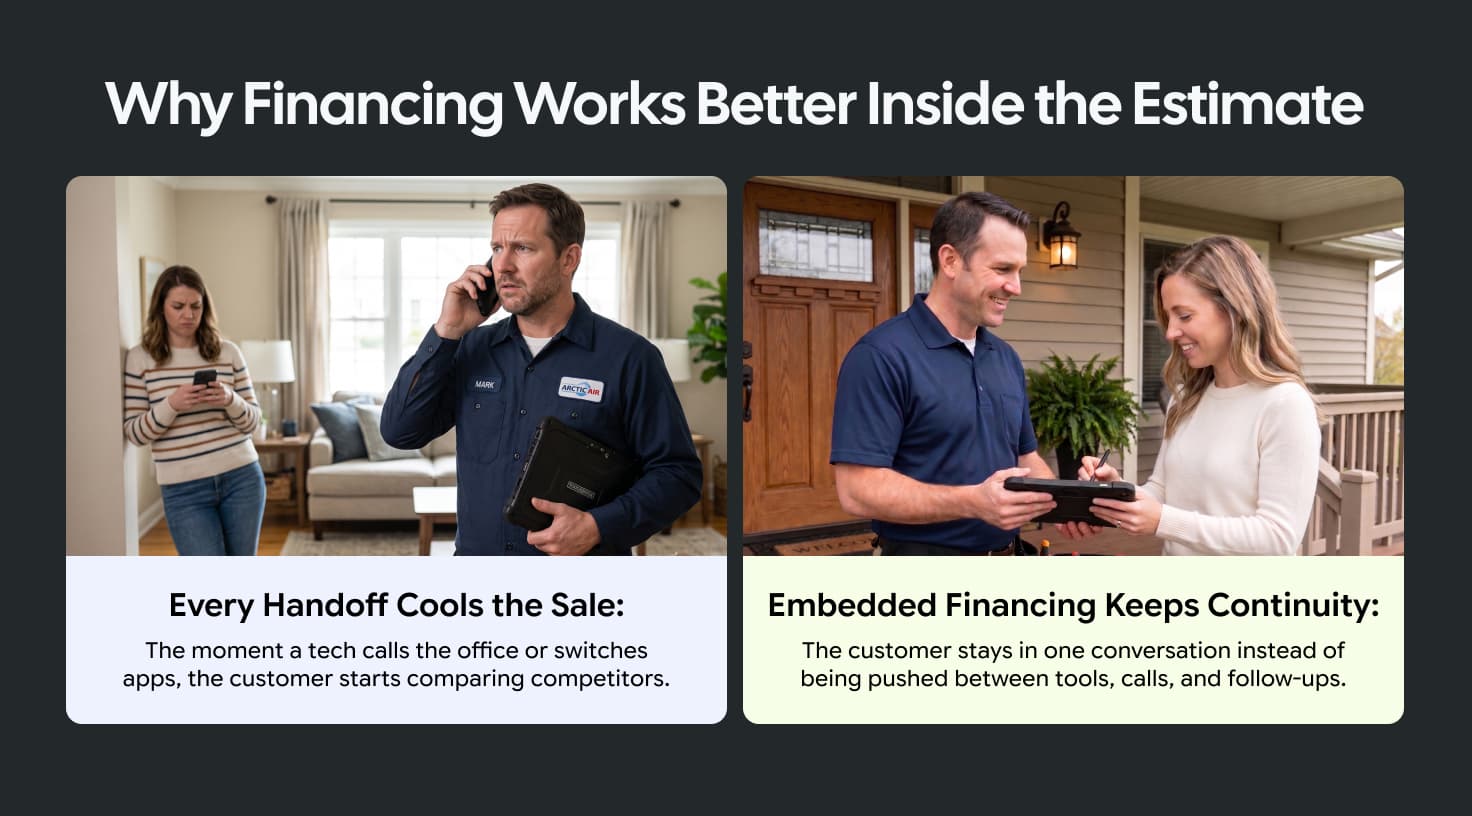
The Moment a Tech Switches Apps or Makes a Phone Call, the Customer Cools Off
Consider what happens when a homeowner asks about financing and the tech has to call the office.
The customer waits. The office looks for information. The tech may need to send a link later or explain the process after leaving the property.
By that point, the customer is no longer focused on the proposal in front of them. They may start comparing companies, searching for other offers, or putting off the decision.
Every additional handoff gives the sale another opportunity to slow down.
Embedded Financing Keeps the Conversation in the Driveway Where It Belongs
When financing is connected to the estimate workflow, the tech can move naturally from the recommendation to the customer's next question without interrupting the conversation.
The homeowner can review the proposal and available options while the technician is still present to answer questions about the equipment, installation, and job scope.
Workiz's consumer financing tools are designed around this field workflow, with financing options connected to estimates and customer records.
The advantage is not simply speed. It is continuity. The customer stays in one buying process instead of being pushed between separate tools, calls, and follow-ups.
HVAC Contractor Financing Best Practices
To maintain high approval rates while protecting your profit margins, your business needs a consistent, structured operational workflow.
Operational Focus Area | Implementation Standard | Business & Margin Impact |
Lending Network Diversity | Pair a prime platform (e.g., Wisetack) with a secondary provider (e.g., Sunbit) | Maximizes approvals across credit profiles from sub-600 to 750+ FICO |
Universal Estimate Presentation | Include payment options in every relevant estimate. | Eliminates technician profiling; lifts repair-to-replace conversion rates |
Early Presentation | Introduce financing during initial diagnostic findings, not after price rejection | Eliminates customer sticker shock and avoids defensive discounting |
How Workiz Helps HVAC Contractors Offer and Manage Financing in the Field
For a busy HVAC team, financing should not mean a disconnected process where estimates, applications, payments, and job records live in different systems. Workiz brings those parts of the job lifecycle together.
Wisetack and Sunbit Integrated Directly Into the Workiz Estimate: Offer Wisetack and Sunbit financing options directly within the Workiz estimate workflow, so techs can keep the conversation moving in the field.
Good/Better/Best Proposals With Financing at Every Tier: Present clear equipment options and payment choices in one proposal, helping customers compare what works best for their home and budget.
Instant Approvals Without Manual Paperwork or Phone Calls: Digital financing workflows reduce paperwork and unnecessary back-and-forth, allowing techs to stay focused on the customer and the job.
Financing Tracked Alongside Scheduling, Invoicing, and Job History in One Platform: Keep financing connected with scheduling and dispatching, estimates, payments, and customer job history on Workiz.